Save My Pre-Approvalof Cornerstone First Mortgage, LLCNMLS #173855
About

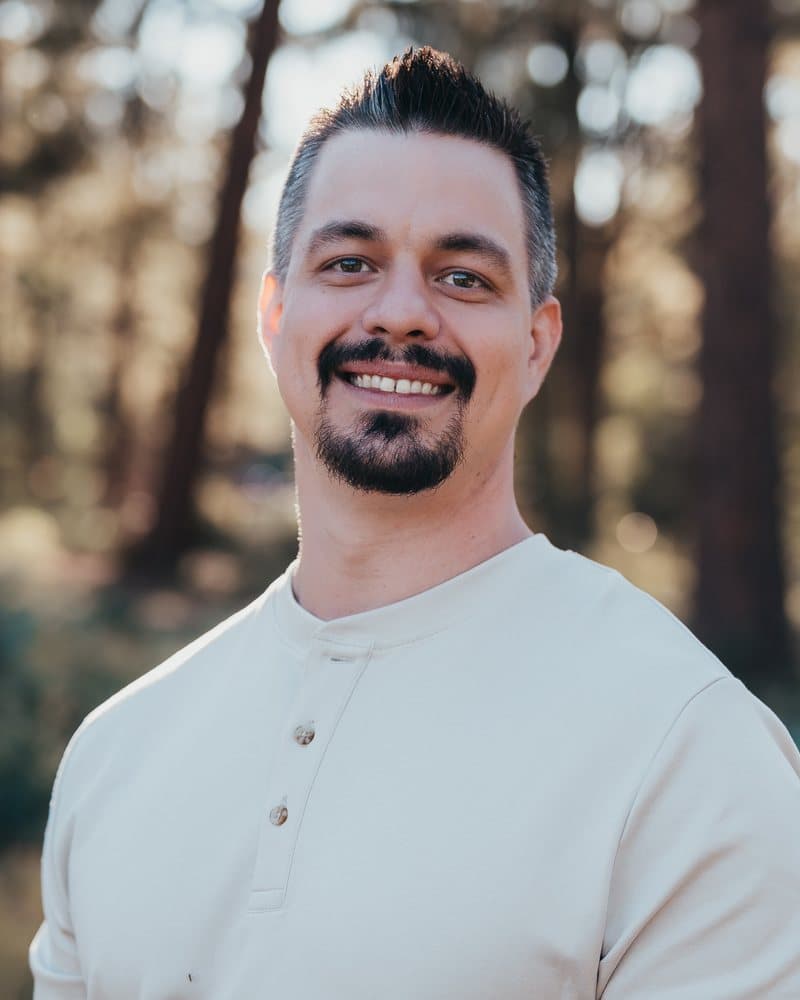
Meet Tanner Cook

I'm a licensed mortgage loan originator at Cornerstone First Mortgage, LLC (NMLS #173855). Save My Pre-Approval is where buyers and real estate agents bring the loans another lender denied, cut or let stall, so I can find the real reason and tell them straight whether it can be saved.

Tanner Cook, Mortgage Loan OriginatorTanner Cook NMLS #2090424Cornerstone First Mortgage, LLC NMLS #1738554.89 · 45 reviews of Tanner Cook on Experience.com

Quick facts

Who I am
Tanner Cook (NMLS #2090424), mortgage loan originator licensed in Arizona, Michigan, Texas and Washington.
Lender
Cornerstone First Mortgage, LLC, NMLS #173855. NMLS record(opens in a new tab)
What I focus on
Second looks: loans denied in underwriting, self-employed and 1099 income, ITIN buyers, investors, tight debt-to-income, condos, and deals with a closing date on the line.
How a file gets placed
Checked against agency programs and 25+ non-QM investors, then, for most files, underwritten in-house by Cornerstone to the guideline it fits.
Who reviews your file

One loan officer, start to finish

Tanner Cook, Mortgage Loan Originator

Tanner Cook

Mortgage Loan Originator

NMLS #2090424(NMLS Consumer Access, opens in a new tab)

  • Second looks after a denial
  • Non-QM & alternative income documentation
  • Saving deals under contract

Tanner works the files other lenders turned down or let stall: self-employed and 1099 income, ITIN borrowers, investors, tight debt-to-income, condos, and deals with a closing date on the line. He finds out exactly why the answer was no, checks the file against the agency and non-QM guidelines Cornerstone can underwrite in-house, and tells buyers and their agents straight whether it can be saved.

Full profile and guides by Tanner
How it works behind the scenes

Why a second look with Cornerstone can change the answer

Underwritten in-house

Cornerstone underwrites most loans with its own underwriters, so a hard file gets a real answer from the people making the decision, not a bank three states away.

No extra lender overlays

Some denials come from a lender’s own rules stacked on top of the guideline. Cornerstone underwrites to the agency or investor guideline as written.

25+ non-QM investors

As a delegated correspondent, Cornerstone works with more than 25 non-QM investors, so a complex file can be matched to the guideline that fits it instead of being forced through one rulebook.

A scenario desk

Complex files can be structured before they are submitted, so the answer is known before a buyer is tied up in a contract for weeks.

Approvals that are already underwritten

Buyers can be fully underwritten before they pick a home. That is a different thing from a pre-qualification letter, and it may help surface problems before you are under contract. The approval is still conditional.

The appraisal may come with you

An existing appraisal can sometimes be transferred to a new lender. It depends on the investor and on how it was ordered, so it gets checked on day one.

Licensing you can verify

Verify my license, Cornerstone's license, and the states each covers on NMLS Consumer Access.

Equal Housing Opportunity

Cornerstone First Mortgage, LLC is an Equal Housing Opportunity Lender. State notices and program disclosures are on our Disclosures & Licensing page.

Talk to me about your file

Call, text, email or book a time. Or start with the one-minute rescue check.

Non-QM programs require alternative income documentation. All loans are subject to underwriting approval, income/asset verification, appraisal, and an ability-to-repay determination. Not all applicants will qualify. Program availability and guidelines are subject to change without notice.